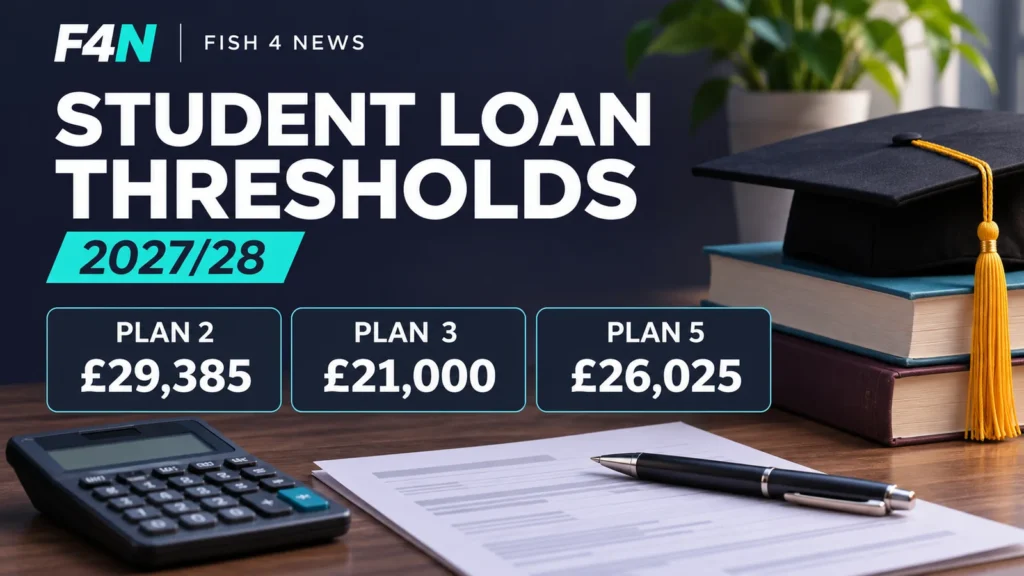
Student loan repayment thresholds for 2027/28 have been confirmed, with Plan 5 graduates in England receiving a higher earnings threshold while Plan 2 and postgraduate loan thresholds remain frozen.
The Student Loans Company announcement, published on 12 November 2026, sets the thresholds for 6 April 2027 to 5 April 2028. The figures apply to relevant borrowers in England and Wales, but the type of loan a person holds determines how much they repay.
Student loan repayment thresholds for 2027/28
| Loan plan | 2027/28 annual threshold | Repayment rate | What changes |
|---|---|---|---|
| Plan 2 undergraduate | £29,385 | 9% above threshold | Unchanged |
| Plan 3 postgraduate | £21,000 | 6% above threshold | Unchanged |
| Plan 5 undergraduate (England) | £26,025 | 9% above threshold | Rises from £25,000 |
These are income thresholds, not the amount of debt a graduate must repay or an annual charge on their full salary. Someone earns above a threshold before repayments become due, and the percentage applies only to earnings above it.
Who is affected in England and Wales?
- Plan 2: generally covers Student Finance England undergraduate borrowers who started courses from September 2012 to July 2023, and Student Finance Wales undergraduate borrowers who began from September 2012 onwards. Certain other loans, including PGCE loans, can also qualify.
- Plan 3: covers postgraduate master’s and doctoral loans in England and Wales. Borrowers can have a postgraduate loan as well as an undergraduate loan.
- Plan 5: generally covers eligible Student Finance England undergraduate and PGCE courses started on or after 1 August 2023, plus certain other eligible loans. It does not replace Plan 2 for new Student Finance Wales undergraduates.
The government’s repayment-plan checker explains the qualifying courses and start dates. Your plan is based principally on the student finance system you borrowed through and the type and timing of your course, not simply where you work today.
How much will graduates repay each month?
The examples below assume a fixed gross annual salary, paid in 12 equal monthly instalments, one loan plan at a time and no bonuses. They use the announced 2027/28 thresholds and round monthly PAYE deductions down to whole pounds, following HMRC’s published payroll method.
| Annual salary | Plan 2 / month | Plan 3 / month | Plan 5 / month |
|---|---|---|---|
| £25,000 | £0 | £20 | £0 |
| £28,000 | £0 | £35 | £14 |
| £30,000 | £4 | £45 | £29 |
| £40,000 | £79 | £95 | £104 |
| £50,000 | £154 | £145 | £179 |
| £60,000 | £229 | £195 | £254 |
Worked example at £40,000: A Plan 2 borrower earns £10,615 above £29,385, so 9% is £955.35 a year, or £79.61 a month before payroll rounding, giving approximately £79 a month. On Plan 5, earnings above £26,025 are £13,975; 9% is £1,257.75 annually, or £104.81 monthly before rounding, giving about £104 a month. A Plan 3 postgraduate borrower pays 6% of £19,000, equivalent to £95 a month.
These are illustrations, not personalised payslip forecasts. Payroll uses pay-period thresholds and whole-pound rounding. A bonus, changing earnings, weekly pay or Self Assessment can alter when and how much is collected. Student loan deductions are taken from gross pay alongside tax and National Insurance, but are calculated separately.
What does the Plan 5 increase mean?
The Plan 5 threshold rises by £1,025, from £25,000 in 2026/27 to £26,025 in 2027/28. Someone earning £30,000 throughout both years would see an illustrative monthly Plan 5 deduction fall from £37 to £29, assuming identical monthly pay. It is the repayment threshold that rises, not the proportion deducted: the 9% rate stays the same.
Plan 2’s £29,385 threshold is set to remain frozen for the three tax years from 2027/28 through 2029/30. That means earnings growth can cause affected borrowers to repay more even though the repayment percentage has not increased.
Why is Wales also freezing Plan 2?
The Welsh Government confirmed on 11 November that its Plan 2 repayment threshold would also remain at £29,385 for 2027/28, 2028/29 and 2029/30. Deputy Minister Cefin Campbell said the shared Student Loans Company and HMRC repayment system could not currently operate different Plan 2 thresholds for English and Welsh borrowers without major technical changes.
That is an important change from Wales’s earlier stated intention not to adopt England’s three-year freeze. The Welsh Government says it did not want to freeze its threshold but considers the change unavoidable under the existing shared system. Welsh undergraduate borrowers are generally still on Plan 2, while many newer English undergraduate borrowers are on Plan 5. The plans differ in other terms too, including the usual write-off period.
Are repayment thresholds the same as interest rates?
No. The repayment threshold determines when salary-linked deductions start. The interest rate determines how quickly interest is added to the outstanding loan balance. A higher interest rate does not, by itself, make the monthly income-based deduction larger.
For Plan 2, the separate lower and higher interest-rate income thresholds stay at £29,385 and £52,885 for 2027/28. These are used to work out the applicable variable interest rate on a Plan 2 balance. They do not mean a borrower starts paying 9% of their entire salary at £52,885.
The published interest-rate schedule for September 2026 to August 2027 uses RPI of 4.1% for Plan 5, while Plans 2 and 3 have different interest calculations and a 6% cap for that period. Those are 2026/27 academic-year interest figures, not an announcement of the interest rates that will apply throughout 2027/28. The 12 November notice confirms repayment thresholds, not new interest rates.
What if you have both an undergraduate and postgraduate loan?
A borrower with an undergraduate loan and a postgraduate Plan 3 loan can repay both at once: 9% above the applicable undergraduate threshold plus 6% above £21,000. At £40,000 annual pay, a Plan 2 plus Plan 3 borrower would therefore pay approximately £79 + £95 = £174 a month, assuming equal monthly salary.
Having two different undergraduate plans does not mean two separate 9% deductions. Repayments are generally calculated using the lowest applicable undergraduate threshold and split between the loan balances according to the rules. The same borrower may nevertheless have an additional 6% postgraduate deduction.
How to check your plan and repayments
- Check your active repayment plan on the official student-loan repayment-plan page and review your payslip to make sure your employer uses the correct plan.
- Use the government’s repayment guidance to understand deductions, including what happens if income varies.
- For payroll calculation details, see HMRC’s published student and postgraduate loan deduction instructions.
Sources
- Student Loans Company, repayment thresholds announced 12 November 2026
- Welsh Government, Plan 2 freeze statement, 11 November 2026
- GOV.UK, which repayment plan you are on
- GOV.UK, how much you repay
- HMRC, student and postgraduate loan deduction tables and rounding guidance
- Student Loans Company, interest rates for 2026/27